Does SBI General Insurance - Super Health Cover Diabetes?

Type 1 vs Type 2 Diabetes: How Coverage Differs
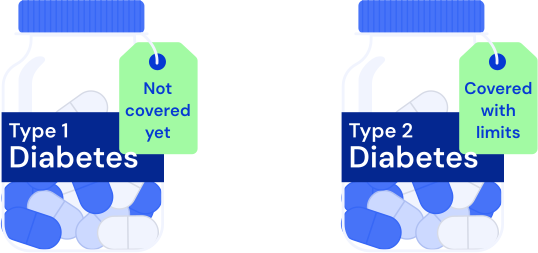
Diabetes is not a single condition. Type 1 and Type 2 carry different implications for your health cover. Type 1 is rarer, more severe, and poorly covered by most plans.
Type 1 vs Type 2 Diabetes: Why Insurers Treat Them Differently
- Type 1 diabetes needs insulin from diagnosis and carries higher hospitalisation risk. Most policies either exclude it or apply long waiting periods.
- Type 2 diabetes is more common and often lifestyle-linked. Some plans cover it faster, particularly through add-ons or riders.
Declare Diabetes as a PED: Do It Correctly
Declare diabetes as a Pre-Existing Disease (PED), or your claim can be rejected.
Buyers often assume diabetes does not count as a PED. IRDAI rules are explicit: non-disclosure is grounds for claim denial or policy cancellation.
If you have diabetes, state it accurately at the point of purchase. Full disclosure keeps your claim valid and points you toward plans built for your condition.
Why Hospitalisation Risk Is the Priority
Hospital bills, not routine insulin, are the real financial threat.
Insulin and daily management add up over time, but the largest financial hit comes from hospital admissions tied to diabetes complications.
For Example:
- Diabetic foot ulcer surgery: ₹40,000–₹2,00,000
- ICU for ketoacidosis: ₹18,000–₹30,000 per day
The hospitalisation limits and waiting periods in SBI General Insurance - Super Health directly shape what you end up paying out of pocket.
 No pressure to buy.No spam.Just unbiased advice.
Use Riders and Add-Ons to Cut Waiting Periods
Some insurers offer add-ons that shorten the Type 2 diabetes waiting period from the usual 2–4 years down to 0–30 days.
Commonly cited options include Care Supreme, Aditya Birla Activ One Max, and a few others.
For Type 1, fast coverage is uncommon but does exist: HDFC ERGO Energy offers Day 1 coverage, one of the few plans that do.
Beyond Diabetes Cover, Check These Policy Details
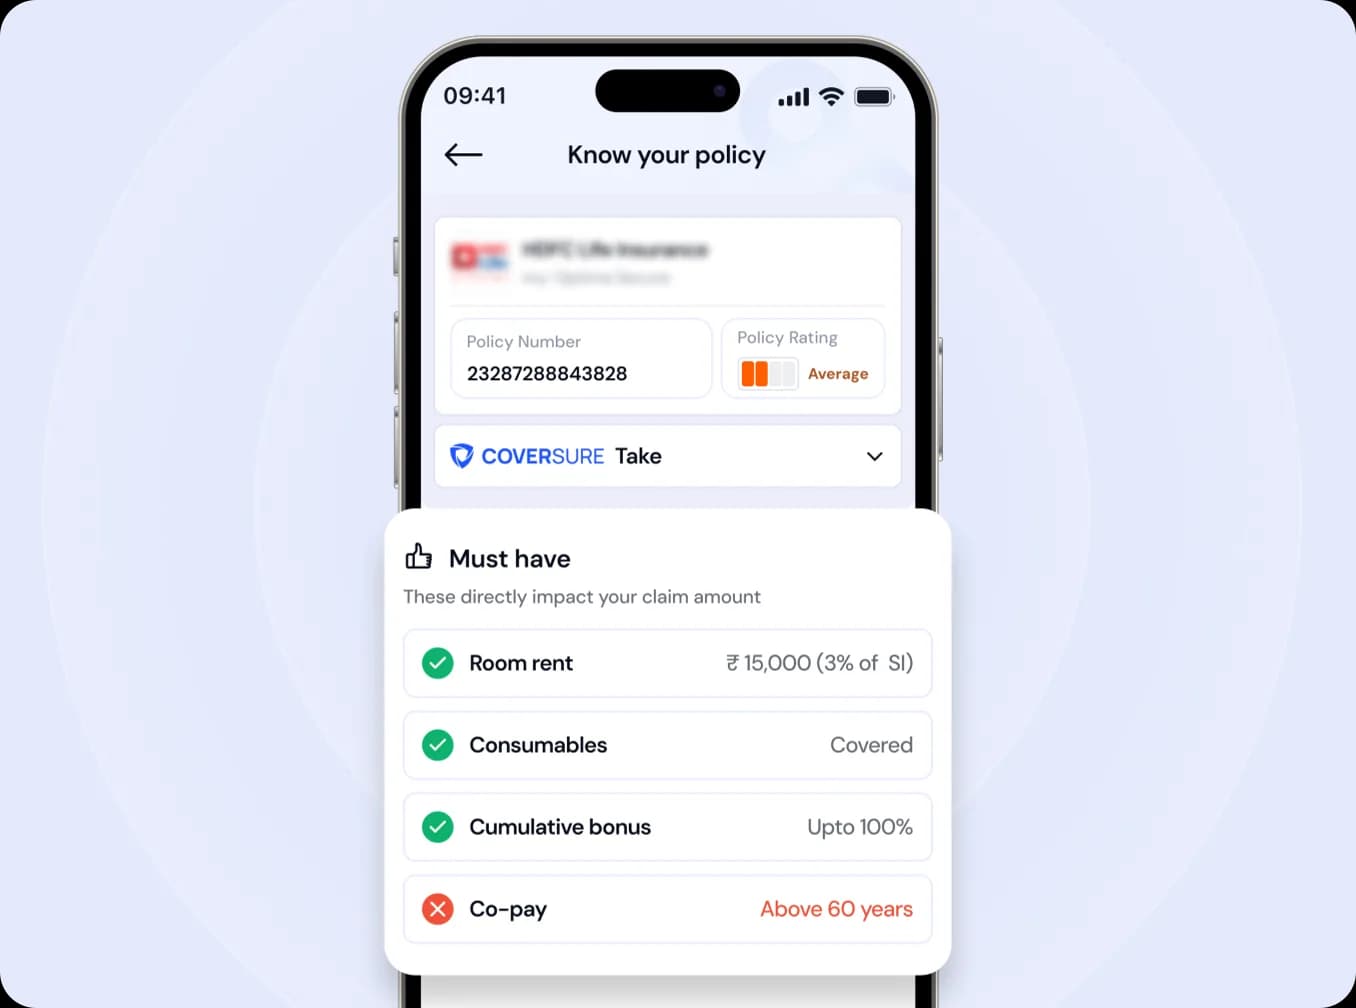
- Pre- and post-hospitalisation days covered
- Room rent and ICU limits
- Sub-limits on specific treatments
- Chronic illness rider requirements
- Co-payment clauses
CoverSure lays all of this out upfront, so there are no surprises at claim time.
What Users Found Using CoverSure
What Our Users Say
“I didn’t realize my policy had a 4-year waiting period for diabetes until CoverSure flagged it.”
“CoverSure helped me find a rider to reduce my wait to 30 days-huge relief!”
“I was surprised that Type 1 was excluded in most plans, but found coverage with HDFC ERGO.”



Reviewed by
Atul SharmaAVP, Founder’s Office at CoverSure · 7+ years in insurance (ex-Tata, Ditto, Cholamandalam)
